
Empower your team with our ESOP/VSOP services in Germany



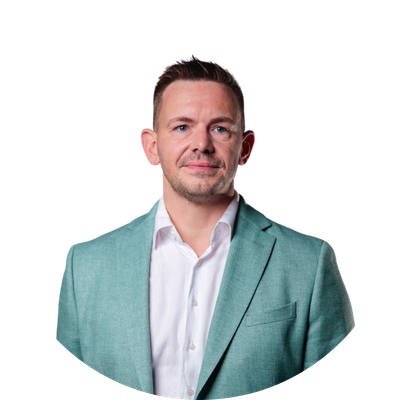
Ready to take the first step? Book a call with me and my team! We’ve helped hundreds of startup founders set up their plans. With our expertise, data insights, and efficient process, you’ll get the best results!
Stephan Meyer · Partner @LEXR Germany · Get in touch →
Find your perfect flat fee plan
VSOP Package
EUR 1,950 (excl. VAT)
This flat fee package includes:
- Expert meeting with our legal experts: strategic planning and advice, discussion of core variables, decision on the most suitable plan
- Drafting of the legal documents including the allocation agreement
- Feedback round, to clarify all open issues and implement the adjustments
- Review of existing legal documents related to the plan
- Guidance for the plan management
ESOP Package
EUR 1,950 (excl. VAT)
This flat fee package includes:
- Expert meeting with our legal experts: strategic planning and advice, discussion of core variables, decision for the most suitable plan
- Drafting of the legal documents including the allocation agreement
- Feedback round to clarify all open issues and implement the adjustments
- Review of existing legal documents related to the plan
- Guidance for the plan management
Employee workshop
EUR 1,800 (excl. VAT)
This flat fee package includes:
- Kick-off session with our legal experts and the management team
- Preparation of the employee workshop according to the management input
- Implementation of the workshop with the company's employees
- Training concept & manual for future internal employee workshops
ESOP and VSOP explained simply
An ESOP (Employee Stock Option Plan) gives employees the right to acquire real share in the company in the future and then, if the start-up is sold (Exit) or goes public (IPO), to participate in the company’s growth. The actual allocation of shares (e.g. in the case of a GmbH) is sometimes subject to strict formal requirements, in particular notarization and the approval of the shareholders. The granting of options has tax implications (possibly the so-called dry-income problem). A VSOP (Virtual Stock Option Plan) gives employees no real shares but virtual shares, serving as a calculation factor. In the event of an exit or IPO, employees receive financial benefits similar to owning real shares, but without actual ownership. VSOPs offer more flexibility and can avoid the tax and formal challenges of ESOPs in Germany.
Why implement an employee ownership plan?
Employee motivation and retention
ESOP and VSOP plans give employees a share in the company’s success, boosting loyalty and reducing turnover.
Performance-based rewards
These plans link employee rewards to company performance, motivating employees to drive business success.
Tailored to your goals
Both ESOP and VSOP plans can be customized to meet your company’s specific goals and employee roles, offering flexible and effective incentive structures
How we set up your participation plan
-
Expert session
In a first session, we discuss the plan’s strategic goals and potential impact, sharing practical insights and current market trends from our extensive experience with employee benefit plans.
-
Contract drafting
Based on our session, we draft legal documents using our tested templates, ensuring the plan aligns with the startup and VC world.
-
Document review
We review existing legal documents to ensure compatibility with the new employee participation plan, identifying and advising on necessary changes.
-
Feedback
We address all legal questions during the feedback round and finalize the legal documents for the employee participation plan.
-
Plan management
We provide a plan management guide to help you maintain the employee benefit plan and meet deadlines effectively.
Why LEXR?
Industry expertise and proven ESOP track record
Benefit from our legal expertise in tech, FinTech, and digital industries. Our extensive experience with ESOP/VSOP ensures your plan aligns with market best practices and industry standards. With numerous successful implementations, we deliver tailored solutions that meet your unique business needs.
Transparent and predictable costs
Enjoy peace of mind with our flat fee packages. Our transparent pricing helps you plan your budget without unexpected costs, ensuring financial clarity and predictability.
Fast and efficient service
Experience swift and reliable ESOP/VSOP implementation. While we use advanced tools to enhance speed, our priority is providing personalized, detailed service that meets your specific business needs.
ESOP addition: Tax ruling
The allocation of genuine shares or options on such shares to an employee generally results in a so-called non-cash benefit. This is treated in the same way as wages for tax and social security purposes. This leads to the so-called “dry-income problem”, as employees have to pay tax on sums of money that they have not yet received in cash. Although special tax regulations exist to prevent taxation at the time of allocation, the applicability of these regulations is highly dependent on the individual case. To ensure that the tax and social security implications of stock options can be planned for both the employee and the company, we recommend obtaining information from the tax office at the place of business. Together with the ESOP, we offer to obtain a call report at cost (costs generally between EUR 650 and 1,600).
More participation plan services
- Consulting on or changes to an existing VSOP / ESOP
- Consulting on the international rollout of a VSOP / ESOP
- Implementation of an international VSOP / ESOP for German employees
- Other participation options for employees (direct shareholdings, dormant shareholdings, establishment of employee investment companies)
Hear it from our happy clients
The cooperation was very good and I can already predict that we will approach LEXR again. We had a good feeling right from the start. This was then confirmed throughout the entire process. We had the feeling that LEXR was part of the deskbird team.
Through the recommendation of another startup founder, we came across LEXR. Michele and the corporate team guided us through the entire process of the financing round. When we write an email, we receive a reply in no time, and time is taken to explain legally complex issues in a simple and understandable way.

VSOP & ESOP FAQ
Section 19a EStG was introduced to ease the burden on start-ups with regard to employee participation. The regulation allows deferred taxation of employee share ownership under certain conditions: Instead of having to pay income tax immediately when the shares are transferred, taxation can be deferred to a later date (e.g. when the shares are sold or after 12 years).
The advantages: Employees do not have to bear the tax burden at a time when they have not yet received any liquidity (“dry income”). This makes early genuine participation more attractive.
The restrictions: Section 19a only applies to genuine business shares or stocks, and only if the company meets certain requirements, including being a maximum of 20 years old, employing less than 1000 employees and complying with certain revenue limits. In addition, Section 19a EStG only applies to income tax. Income from a company shareholding is still subject to social security contributions, any social security contributions due are included in the lump-sum pension contribution.
In practice, Section 19a EStG is therefore not applicable to every company or every shareholding plan. A careful examination and, if necessary, consultation with the tax office is recommended.